

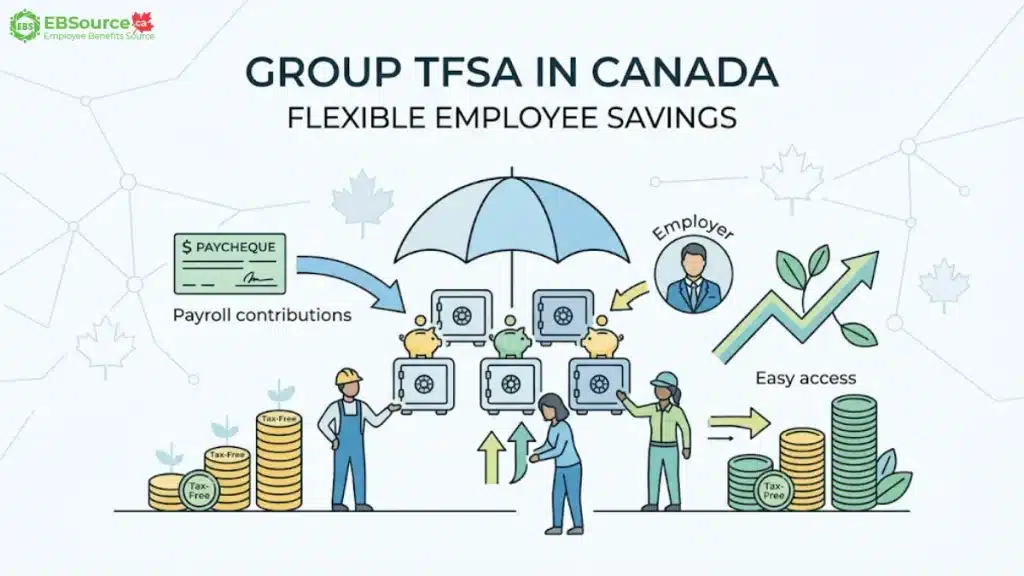
A Group Tax-Free Savings Account (Group TFSA) is a workplace savings arrangement in which employers send contributions to employees’ individual TFSAs through payroll. Each employee is the account holder, while the financial institution (the “issuer”) opens and administers each account. Despite the name, there is no special “Group TFSA” account registered with the CRA at the employer level.
A Group TFSA can complement a pension or Group Registered Retirement Savings Plan (Group RRSP) by giving employees another way to save for short- and long-term goals. This guide covers eligibility, matching design, payroll setup, contribution-room controls and launch preparations.
Why Do Employers Offer a Group TFSA?
The plan offers value on both sides. Employers may use a group TFSA as an employer-sponsored benefit to broaden their savings benefits and support recruitment, retention or financial-wellness goals. Because employees can withdraw at any time, it meets needs that retirement-focused plans do not. Beyond that, employees can benefit from tax-free investment growth and generally tax-free withdrawals.
The table below shows who gains from each benefit and why it matters:
| Benefit | Who gains | Why it matters |
|---|---|---|
| Recruitment and retention appeal | Employer | Adds a flexible savings option for employees who want access to savings before retirement |
| No employer-level TFSA registration | Employer | The issuer registers and administers each TFSA; the employer keeps plan, payroll and reporting duties |
| Predictable contribution budget | Employer | A match formula and cap limit the employer’s contribution; payroll taxes and fees may be extra |
| Financial-wellness support | Both | Gives employees another way to build funds for short- or long-term goals |
| Employer match | Employee | Extra savings (taxable, and counts toward TFSA room) |
| Tax-free growth and withdrawals | Employee | Generally tax-free under Canadian TFSA rules |
| Potential group pricing | Employee | Some providers advertise lower fees than retail; compare the actual fees |
| Immediate vesting and portability | Employee | Contributions “vest” immediately, meaning they belong to the employee from the first deposit and go with them if they leave |
Which Employees Can Employers Enrol in a Group TFSA?
HR teams should keep federal TFSA eligibility separate from the employer’s own plan conditions. For federal purposes, a person generally must be resident in Canada for income tax purposes, be at least 18 and have a valid SIN.
Employers may also set workplace eligibility conditions, such as a minimum service period before an employee qualifies for matching contributions. However, those conditions cannot override the CRA’s TFSA eligibility requirements.
If the provider allows spouses to take part, HR should confirm the plan terms and also explain that each participating spouse must independently meet TFSA eligibility requirements and use their own contribution room.
Before enrolment, HR should check four situations that can change an employee’s eligibility or contribution arrangements:
How Should HR Handle Age-of-Majority Requirements?
Keep in mind that, in provinces and territories where the age of majority is 19 (British Columbia, New Brunswick, Nova Scotia, Newfoundland and Labrador, Yukon, the Northwest Territories and Nunavut), an individual may open a TFSA only after turning 19. They still earn the room for the year they turned 18.
How Should HR Communicate the Plan to Older Employees?
TFSAs have no maximum age for contributions and no required withdrawals. RRSP contributions must stop at the end of the year an employee turns 71, but that employee can keep saving in a group TFSA if they remain eligible and have room.
HR action: If part of your workforce is older, describe the group TFSA in enrolment materials as a savings option that stays available after RRSP contributions end.
What Should HR Communicate When Enrolling New Canadian Residents?
An eligible new resident gets the full TFSA dollar limit for the calendar year in which they become resident. The annual amount is not reduced for the months before they arrived. New residents still must be at least 18 to earn room.
How Should Payroll Respond When an Employee Becomes a Non-Resident?
An employee who becomes a non-resident can generally keep an existing TFSA, and Canada still treats it as a TFSA. However, the employee’s new country of residence may tax TFSA income, gains or withdrawals under its own rules.
Keeping the account is not the same as continuing to contribute to it. Contributions made after the employee becomes a non-resident, including employer matches, can trigger tax for the employee:
- No new room: No TFSA contribution room builds up in any year the employee is a non-resident for the whole year.
- 1% monthly tax: Contributions made while non-resident are generally taxed at 1% per month on the full amount for each month they stay in the account. The tax continues until the full non-resident contribution is withdrawn, or until the employee becomes a Canadian resident again. A partial withdrawal does not reduce the tax.
- Possible second tax: If the same contribution also exceeds the employee’s available room, a separate 1% monthly excess-contribution tax can apply.
Payroll action: Employers should have a process to stop TFSA payroll contributions as soon as an employee confirms they have become a non-resident for Canadian tax purposes.
Source: Opening a TFSA – Government of Canada

What the Group TFSA Ownership Structure Means for Employers
Because the employee owns the account, the employer’s rights are limited in three ways: the account must be maintained for the employee’s exclusive benefit, the employer cannot recover money once it has been validly contributed, and the employer cannot independently verify the employee’s available personal contribution room.
- The account exists only for the employee’s benefit. CRA rules prohibit anyone other than the holder or the issuer from controlling when and how much money is withdrawn, or how the funds are invested.
- The employer cannot take money back. Once an amount has been validly contributed, the employer has no right under the TFSA arrangement to direct a withdrawal or recover the money. Any payroll overpayment must be recovered separately, under employment, contract and payroll rules.
- The employer cannot independently verify the employee’s contribution room. The CRA does not give employers this information. The employee is responsible for tracking room across all personal and workplace TFSAs.
Employers can still set program rules, such as matching conditions, as they would for other workplace retirement plans. They do not give the employer ownership of the TFSA or authority to direct a withdrawal. Actual access to an investment can still depend on the issuer’s terms and the investment itself, such as a GIC maturity restriction.
What Happens to the Group TFSA When an Employee Withdraws or Leaves?
Standard TFSA rules generally govern withdrawals and what happens after employment ends.
Withdrawals
When an employee withdraws, the amount comes out tax-free and is not income, and the withdrawn amount is normally added back to the employee’s contribution room the following calendar year. The workplace retirement program may add administrative conditions.
For example, RBC’s group TFSA supports a withdrawal-notification process and allows a sponsor to suspend future matching contributions for a period after an employee withdraws funds. Those are program terms, not restrictions on the employee’s access to their own money.
Termination or Retirement
On termination or retirement, the account does not close because the employment relationship ends. Depending on the provider’s arrangement, the assets can typically remain in an individual TFSA with the same issuer (for example, RBC’s group TFSA keeps the same account numbers), be transferred to another TFSA, or be withdrawn tax-free.
Group TFSA vs Group RRSP vs DPSP: What’s the Difference?
The main differences are when tax applies, how employer contributions are treated through payroll, and when employees can access the money. In general, a Group Tax-Free Savings Account offers tax-free withdrawals and no retirement lock-in; a Group Registered Retirement Savings Plan defers tax until withdrawal and gives the employee a deduction; and a Deferred Profit Sharing Plan (DPSP) is an employer-funded profit-sharing plan that may include vesting conditions.
| Feature | Group TFSA | Group RRSP | DPSP |
|---|---|---|---|
| Employee contributions | After-tax; never deductible | Deductible within RRSP deduction room; payroll deductions can reduce income tax withholding but not CPP/EI | None; employer-only |
| Growth | Tax-free | Tax-deferred | Tax-deferred |
| Withdrawals | Tax-free; not income | Taxed as income | Taxed as income |
| Contribution room | Cumulative CRA TFSA room | Personal RRSP deduction limit, including carry-forward and pension adjustments | Statutory limits; creates a pension adjustment that reduces next year’s RRSP room |
| Locking-in / vesting | Not locked in by law; the employee owns contributions immediately. Access may depend on the issuer’s terms and the investments held | Generally accessible; some employer conditions | Vesting permitted up to 2 years of membership |
Terms used in this table:
- RRSP deduction room: The maximum an employee can deduct for RRSP contributions in a year, based mainly on earned income from the previous year plus any unused room carried forward.
- CPP/EI: Canada Pension Plan contributions and Employment Insurance premiums, which employers and employees both pay through payroll.
- Statutory limits: Maximum contribution amounts set in the Income Tax Act.
- Pension adjustment (PA): The value of DPSP or pension plan contributions for the year. It reduces the employee’s RRSP room for the following year.
DPSP contributions are also typically tied to employer profits.
When Should an Employer Add a Group Tax-Free Savings Account?
The right workplace savings arrangement depends on what the employer wants its contributions to achieve.
A Group Tax-Free Savings Account may be worth considering for employees who value flexible access or who receive less immediate value from an RRSP deduction at their current tax rate; future tax rates, savings goals and available contribution room still matter.
A Group Registered Retirement Savings Plan may suit retirement-focused saving, particularly when employees can benefit from the immediate tax deduction.
A Deferred Profit Sharing Plan may support retention goals because employer contributions can be subject to a vesting period of up to two years.
| Employer goal | General consideration |
|---|---|
| Flexible savings employees can use for any purpose | Group TFSA |
| Retirement savings with an immediate deduction | Group RRSP |
| Retention through vesting | DPSP |
| Lowest payroll cost on employer contributions | DPSP (generally no CPP/EI on employer contributions); compare group RRSP treatment separately |
| Younger or lower-income workforce | Group TFSA may be worth comparing |
| Older workforce, including employees past RRSP contribution age | Group TFSA, as no maximum contribution age applies |
Many employers combine a group TFSA with another plan rather than choosing only one. Because the payroll treatment of employer money varies between these plans, confirm the specific CPP/EI (and, in Quebec, QPP/QPIP) outcome for your chosen structure before setting a match formula.
A group TFSA can complement your workplace retirement offering, but it does not have to be the starting point. Before choosing a combination, compare small business retirement plans in Canada based on your contribution budget, administrative capacity and whether the owner needs to participate.
What Should Employers Confirm Before Launching a Group TFSA?
Before launch, the employer needs to decide:
- Design: Eligibility, matching formula, caps and pause conditions are documented.
- Budget: The approved budget covers the promised deposits, the employer’s CPP/EI (or QPP/QPIP) on the match and any provider fees.
- Accounts: The issuer has confirmed account opening and any required authorization.
- Contribution controls: Employees know how to check their room and stop or change deductions.
- Payroll: Employee deductions, employer funding and fees are each set up and tested separately.
- Testing: You have run a test payroll and confirmed that the provider received and recorded the correct contributions.
- Provider terms: Fees, investment access, rejected deposits and service responsibilities are understood.
- Offboarding: Withdrawal, termination and residency-change procedures are documented.
Ask HR, payroll and the provider to approve the same implementation brief. Resolve open questions before announcing the first contribution date. Startups setting a first match can use the step-by-step startup retirement planning guide to confirm the full cost fits the funding the company has already secured.
How Can Employers Help Prevent Group TFSA Over-Contributions?
Employers should include contribution-room tracking in the enrolment process by asking employees to confirm that scheduled employee and employer deposits fit within their available room across all personal and Group TFSAs.
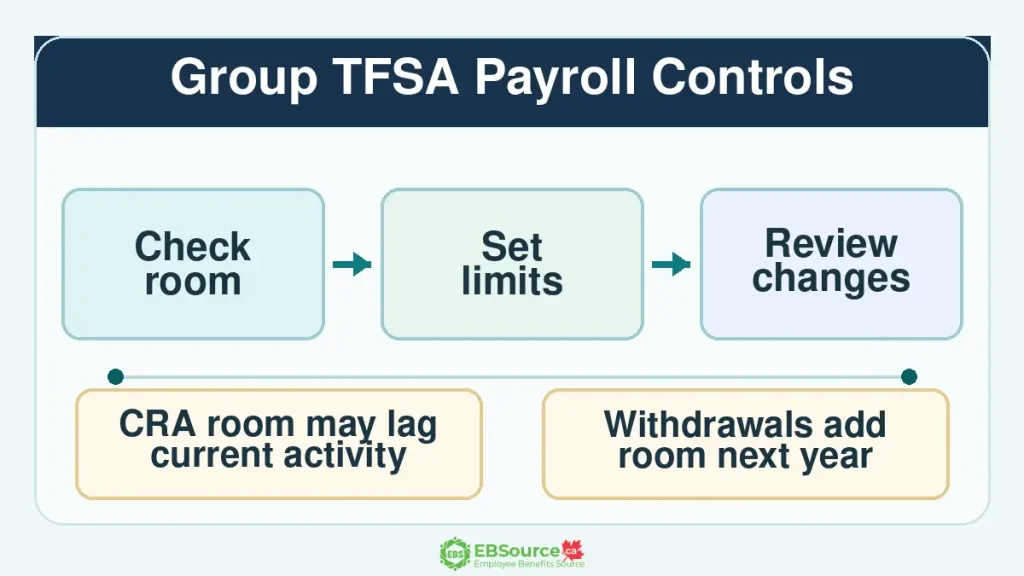
Payroll records show only workplace contributions, and the CRA’s account information is not updated in real time. Employees therefore need to confirm their own room, and employers need a clear way for them to change or pause deposits.
A practical control process should cover three stages:
Before Enrolment
- Show the employee the combined scheduled employee and employer deposits.
- Ask them to confirm that the schedule fits their available room.
- Explain that deposits to any other personal TFSAs also count.
- Provide a clear process for changing or stopping contributions.
During Participation
- Show workplace contribution totals on payroll or provider records that employees can access.
- Remind employees to review their room before increasing deductions.
- Set a cutoff and effective date for changes.
- Check that the provider received the same amounts payroll sent.
- Ask employees to confirm their contribution choices before restarting paused deposits.
When a Problem Is Reported
- Pause or adjust upcoming deposits where operationally possible.
- Check which deposits have already been sent to the provider and which are still pending.
- Give the employee a transaction record.
- Refer account corrections or withdrawals to the issuer.
- Follow the documented matching policy rather than improvising a replacement benefit.
Note that these administrative safeguards reduce the risk but do not guarantee an employee will remain within their personal limit.
Source:
FAQs about Group Tax-Free Savings Account in Canada
What Is the TFSA Contribution Limit for 2026?
The 2026 annual TFSA dollar limit is $7,000. There is no separate limit for workplace TFSAs, and an employee’s available room may be higher or lower than $7,000.
For an eligible resident, the basic calculation is: Current-year dollar limit + unused prior-year room + prior-year withdrawals – current-year contributions across all TFSAs.
Employee contributions and the employer match both count toward this total.
What Happens If an Employee Over-Contributes or Replaces a Withdrawal Too Soon?
Excess contributions generally attract a tax of 1% of the highest excess amount in each month. The employee should promptly review the excess with the issuer; merely stopping future payroll contributions may not correct an existing over-contribution.
An ordinary withdrawal restores room on January 1 of the following calendar year, not immediately. Replacing it in the same year requires other available room. For an account move, ask the receiving issuer to arrange a direct TFSA transfer rather than withdrawing and redepositing the money yourself.
Do Group TFSA Payroll Deductions Reduce Income Tax?
No. Employee contributions come from after-tax pay and are never deductible. Unlike group RRSP deductions, they do not reduce income tax withholding. The benefit comes later, because growth and withdrawals are generally tax-free.
How Are Employer Group TFSA Contributions Taxed and Reported?
Employer-funded Group TFSA contributions are generally cash taxable benefits. Employers must calculate applicable income-tax withholdings, CPP contributions, and EI premiums, depending on the employee’s circumstances and annual limits. These taxable benefits should be reported in the correct T4 fields.
In contrast, employee contributions come from after-tax pay and do not create an additional taxable benefit. Employers should handle these two types of contributions separately and clarify how an employer match can impact an employee’s take-home pay.
Comparing a Group TFSA with other plans? These guides explain how each one handles employer money, vesting and access: