Government Benefits in Canada: How They Fit With Workplace Coverage


Canadian employees may receive support from two separate systems: government programs and employer-sponsored benefits. Government programs may replace income, provide public health coverage, reduce taxes, or support retirement. Workplace plans may supplement that support, but each system applies its own eligibility rules.
Start with the situation that matches your needs below. This guide explains the main public programs, how they interact with workplace benefits and what to do next.
Government Benefits at a Glance
| Your situation | Public programs to explore | Also check at work |
| You lost your job | EI regular benefits | Final pay, outstanding vacation pay and any termination or severance entitlement that may apply |
| You cannot work because of illness or injury unrelated to work | EI sickness benefits | Paid sick leave |
| You have a work-related illness or injury | Provincial or territorial workers’ compensation | Injury reporting and return-to-work support |
| You are having or adopting a child | EI maternity and parental benefits, or the Québec Parental Insurance Plan (QPIP) | Employer top-up and benefit continuation |
| You need time off to care for someone critically ill, injured or nearing the end of life | EI caregiving benefits | Job-protected leave and any employer-paid leave or top-up that may be available |
| You have a disability or prolonged impairment |
CPP disability or QPP disability;
Canada Disability Benefit; Disability Tax Credit |
Long-term disability coverage and accommodation |
| You need help with dental costs | Canadian Dental Care Plan or provincial or territorial dental programs | Access to your own or a family member’s dental plan |
| You work and have a low income | Canada Workers Benefit; Canada Groceries and Essentials Benefit | Accurate pay records for your tax return |
| You are planning retirement |
CPP/QPP
Old Age Security and Guaranteed Income Supplement |
Workplace pension or savings plans |
Use this overview to identify programs to investigate. Each has separate eligibility rules, and listed supports may not all be payable together.
What Are Government Benefits for Employees in Canada?
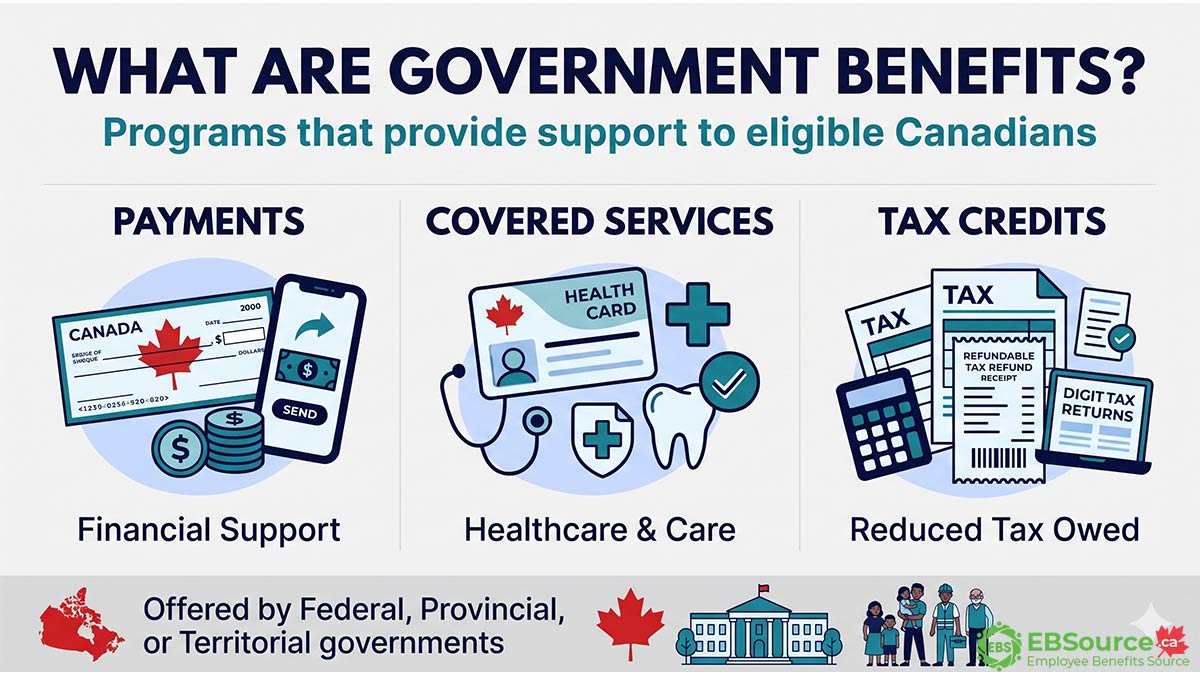
Government benefits for employees are publicly administered payments, services or tax credits that may support income, health, family needs, disability or retirement. They are separate from employer-sponsored benefits, although both systems may respond to the same work or life event.
Which Government Programs Are Connected to Work and Payroll?
The main employment-related public programs provide retirement income, temporary income support or protection for work-related injuries and illnesses. They include:
- Employment Insurance (EI): temporary income support for eligible workers facing job loss or qualifying medical and family situations.
- Canada Pension Plan (CPP) and Quebec Pension Plan (QPP): retirement, disability and survivor benefits under their respective contribution and eligibility rules.
- Quebec Parental Insurance Plan (QPIP): maternity, paternity, parental and adoption benefits for eligible Quebec residents.
- Workers’ compensation: support for covered work-related injuries and illnesses through the applicable compensation system.
Vacation, public holidays and job-protected leave are employment standards rather than income programs. Use the Employment section for those rights and the Statutory benefits hub for detailed program comparisons.
Which Other Government Benefits May Support Employees?
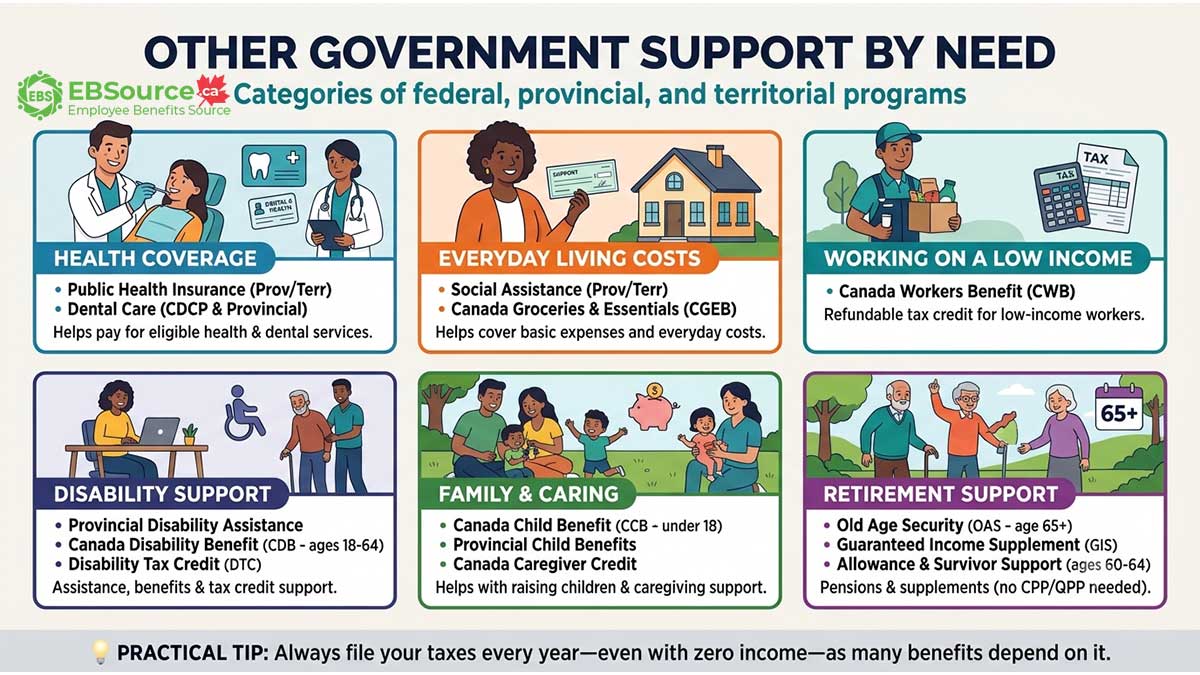
Government support can help with health costs, living expenses, raising children, taxes and retirement. Some programs are federal, while others depend on your province or territory.
Health or Dental Costs
Public health and dental programs help pay for eligible services. Coverage depends on the program, where you live and your circumstances.
- Public health insurance (provincial and territorial): covers medically necessary hospital and doctor services for eligible residents. Prescription drugs and other services follow separate coverage rules. In Quebec, RAMQ health insurance and public prescription drug insurance have different eligibility requirements.
- Canadian Dental Care Plan (CDCP) (federal): helps eligible residents pay for dental care. Access to private dental coverage generally makes you ineligible for the CDCP, even if you decline it. (Source)
- Provincial and territorial dental programs: provide targeted support for eligible groups. Examples include Healthy Smiles Ontario and the Ontario Seniors Dental Care Program.
Support For Employees With Low Income
If you are working but earning a low or modest income, you may be eligible for federal tax credits and benefits designed to supplement your earnings and assist with everyday living costs.
- Canada Workers Benefit (CWB): a refundable tax credit for eligible low-income workers and families. A refundable credit can provide a payment even when you owe no income tax. Your entitlement depends on earnings, family circumstances and other requirements.
- Canada Groceries and Essentials Benefit (CGEB): a tax-free quarterly payment for eligible individuals and families with low or modest incomes. It replaced the GST/HST credit in July 2026.
- Social assistance: financial help based on need, with income, asset and other requirements that vary by jurisdiction. Ontario Works is one example.
Disability-Related Support
Disability support may provide monthly income, tax relief or help with living costs. Approval for one program does not automatically qualify you for another: each applies its own disability and eligibility rules.
| Program | What it provides | Main eligibility checks |
| CPP disability / QPP disability | Monthly payments to eligible contributors | Contributions, age and the plan’s disability definition |
| Canada Disability Benefit (CDB) | Income-tested monthly support for eligible people aged 18 to 64 | DTC approval, family income, residence/status and required tax returns |
| Disability Tax Credit (DTC) | A non-refundable credit that reduces income tax; an unused amount may be transferred to an eligible supporting family member | The effects and duration of an impairment under DTC rules |
| Provincial or territorial disability assistance | Financial support and, in some programs, health benefits | Local disability, income, asset and residence requirements |
Disability Support Programs in Canada
If you are considering the CDB: check your DTC approval first. You must also meet the CDB’s other requirements, including tax filing for yourself and your spouse or common-law partner, where applicable. DTC approval alone does not enrol you in the CDB. (Source)
Family and Caregiving Support
Family and caregiving programs can help with the costs of raising children, replace some income during time off to provide care, or reduce tax for eligible caregivers.
- Canada Child Benefit (CCB): a tax-free monthly payment for eligible families raising children under 18.
- Provincial and territorial child benefits: additional support under local rules. Some payments are combined with the CCB; others are paid separately.
- EI caregiving benefits: temporary income replacement for eligible people who take time away from work to care for or support someone who is critically ill or injured, or needs end-of-life care. These include family caregiver benefits for children or adults and compassionate care benefits.
- Canada Caregiver Credit: a non-refundable tax credit for eligible people supporting a spouse, common-law partner or dependant with a physical or mental impairment.
If you need time off to provide care: check EI caregiving benefits for income support and your jurisdiction’s job-protected leave rules separately. Qualifying for payments does not automatically establish your right to leave.
Retirement Support
OAS and related benefits can provide retirement support without relying on your CPP/QPP contribution history.
- Old Age Security (OAS): a monthly pension for eligible people aged 65 or older who meet legal-status and residence requirements. Income can affect the amount payable.
- Guaranteed Income Supplement (GIS): an additional non-taxable monthly payment for eligible low-income OAS recipients.
- Allowance and Allowance for the Survivor: support for certain eligible low-income people aged 60 to 64, depending on their spouse’s circumstances or whether they are widowed.
Public retirement benefits should be reviewed separately from an employer pension, Group RRSP, DPSP or another workplace retirement plan.
Where Do Employees Apply?
Start with the benefit you need, then find out who runs it. The agency that runs a program is usually where you apply. Three groups handle most programs:
- CRA: tax returns and benefits it manages, such as the CCB, the CGEB, the Canada Workers Benefit and the Disability Tax Credit. The CRA also administers many provincial and territorial tax credits.
- Service Canada: programs it manages, such as EI, CPP, OAS and the Canada Disability Benefit.
- Your province or territory: health cards, social assistance and workers’ compensation. Quebec has its own portals for Quebec-only programs.
Accounts such as My Service Canada Account and CRA My Account let you check a claim, update your details or see payments. Some programs let you apply there, and others don’t. Follow the program’s official instructions before you assume the account is the starting point.
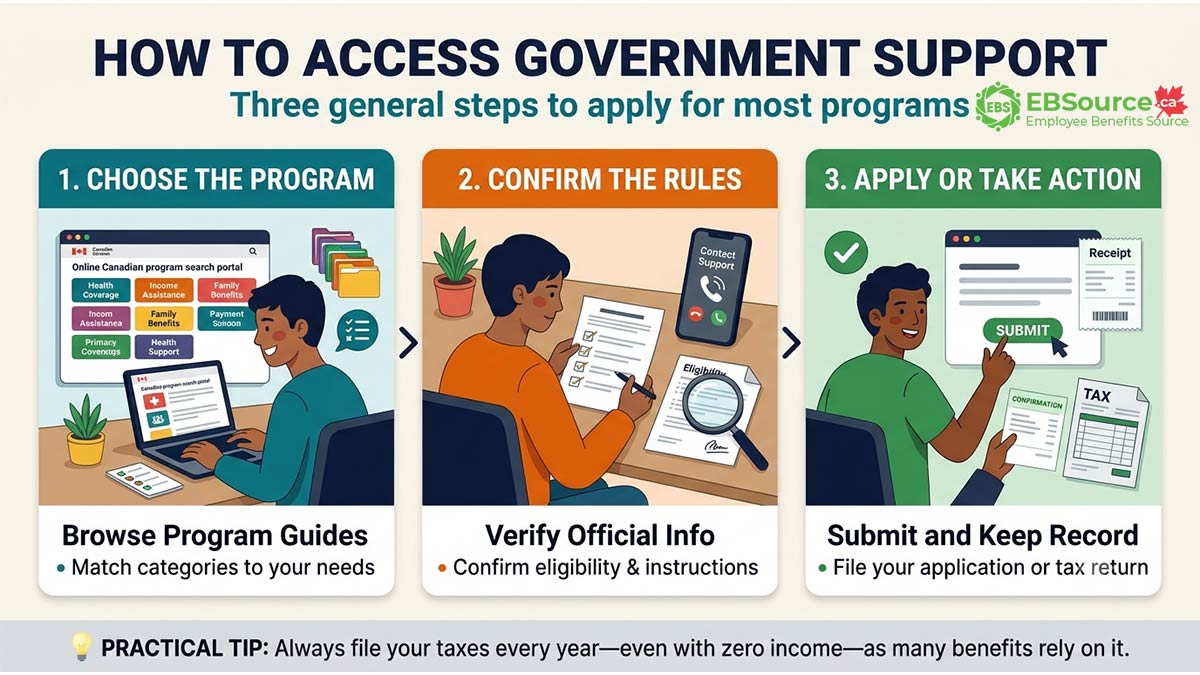
Three common starting points are:
- Choose the program. Use the categories above to identify support that may fit your situation.
- Confirm the rules. Check the official eligibility, application and reporting instructions. Use the linked EBSource guide if you need an explanation.
- Take the required action. Apply, file your tax return or follow the enrolment instructions. Keep your confirmation.
Note: The employer or workplace insurer does not decide eligibility for a government program. The government administrator does not decide eligibility under the employer’s insurance contract.
If you are unsure which federal program to check, use Canada’s Benefits Finder. For provincial or territorial support, follow the relevant jurisdiction’s benefits website.
How Can Government and Workplace Benefits Interact?
Government and workplace benefits often cover the same event, such as illness, disability, leave or retirement. Some workplace benefits add to public support. Others are reduced by it. The contract or plan rules decide which applies.
Workplace Benefits May Supplement Public Support
Workplace coverage can fill gaps that public programs leave. Examples include:
- Employer top-up: Some employers add to EI payments during maternity or parental leave.
- STD and LTD: Short- and long-term disability plans can provide income during illness or disability. Group disability insurance is one layer to check alongside public programs.
- Employer health and dental plans: These can cover costs that provincial health or dental programs do not. Check how your plan fits with any public dental program you use.
- Workplace retirement plans: A pension, Group RRSP or DPSP can add to CPP/QPP and OAS income.
One Payment May Reduce Another
A workplace disability plan may account for CPP disability, QPP disability or workers’ compensation payments when it calculates its own benefit. The result depends on the contract. (Source)
What to do:
- Search your benefits booklet. Look for “other income,” “offset”, and “integration.”
- Ask the plan administrator to explain in writing. Ask which government payments the plan counts and how it counts them.
A Backdated Payment May Mean Repaying Your Insurer
If a retroactive government payment covers a period your insurer already paid for, the insurer may recalculate its benefits and require repayment under the policy. Ask the insurer how it treats a retroactive or lump-sum payment before you apply for a government benefit or receive a decision. Keep your decision letters, because they show the dates and amounts the insurer may ask about.
When Can Public or Workplace Payments Change?
A payment can change or stop when your circumstances change, when information on file is out of date, or when a required step is missed. Each program sets its own rules. Work changes often trigger these updates, so check them whenever your job, hours, or leave status change.
| Trigger | What may be affected |
| Starting or stopping work | EI, disability benefits, income-tested benefits |
| Change in earnings | EI, CWB, CDB, GIS, other income-tested benefits |
| Marital status | Child and family benefits, CWB, CDB, GIS |
| Child custody or care arrangement | Child and family benefits, EI caregiving benefits |
| Moving province | Provincial benefits, credits and coverage |
| Leaving Canada | EI, CDB, CDCP, OAS, provincial programs |
| Change in disability status, where relevant | CPP disability, QPP disability, LTD, workers’ compensation, provincial disability assistance |
| Receiving another income benefit | LTD, EI, income-tested benefits |
| Failure to file a tax return | CWB, CGEB, CDB, other tax-based benefits and credits |
| Failure to complete required reports | EI, LTD, workers’ compensation, CDCP and provincial programs |
Common triggers
How to Report a Change
When your situation changes, report it to each program or insurer that needs the update. This helps prevent interrupted payments and overpayments.
- Identify the administrator for each payment. This may be the CRA, Service Canada, a provincial or territorial program, a workers’ compensation board, an insurer or plan administrator, or your employer.
- Report the change to each administrator that needs it. Updating payroll, the CRA or Service Canada does not automatically update every other system.
- Report changes by the program’s deadline. Use the contact method in your decision letter or on the program’s official page.
- Keep a record. Save confirmation numbers, letters and the dates of your updates.
Which Costs May Still Be Uncovered?
You may still face health bills or lost income after public programs and workplace benefits pay their share. Check what is covered, how much you will receive and when support starts or ends.
Health and Dental Expenses You May Need to Pay
Coverage does not always pay the full bill. Before treatment or a purchase, check the eligible amount and what you must pay yourself.
| Expense | Possible gap and what to check |
| Prescription drugs | Your drug may be excluded or partly covered. Check public and workplace drug coverage, approval requirements and your share of the cost. |
| Dental care | You may owe a deductible, co-payment or amount above the plan’s accepted fee. Ask for an estimate under your dental coverage before treatment. |
| Vision care | Public coverage may be limited, and workplace benefits may cap reimbursement. Check your health plan’s vision benefits for dollar limits and claim frequency. |
| Therapy and other treatments | Check eligible practitioners, referral rules and remaining annual coverage limits. |
Health and Dental Costs to Check Before You Spend
Income and Payment Gaps to Plan For
Income benefits may pay less than your usual earnings or arrive after bills are due. Separate the amount you expect from the dates you can rely on it.
| Possible gap | What to check |
| Lower income | Your payment after tax and any reductions for other income |
| Waiting before benefits start | Your coverage start date, first payable day and employer pay available during the wait |
| Payment delays | Expected arrival date and any missing documents; processing time is separate from a waiting period |
| Support ending too soon | Maximum payment duration, eligibility reviews and your next possible source of support |
Income Gaps and Payment Dates to Check
For workplace income protection, check your disability plan’s payment rules, including benefit limits and reductions for other income. Do not assume two plans will cover the full bill or replace your full pay.
Choose the program that matches your situation, confirm its current requirements on the official website, and check any workplace payment or coverage before budgeting for both.
FAQs about Government Benefits in Canada
Are government benefits in Canada taxable?
Some government benefits are taxable, and others are tax-free. EI benefits and CPP retirement payments are taxable, while the CCB and CGEB are tax-free. Workers’ compensation benefits generally must be reported on your tax return, with a corresponding deduction. Check the official tax guidance for each payment.
What happens to my benefits if I move to another province or territory?
Federal benefits generally continue when you move within Canada, but provincial or territorial payments and coverage may change or end. Your former health plan generally covers insured hospital and doctor services during the new plan’s waiting period, up to three months. Drug, dental and income support follow separate rules and do not automatically transfer to your new province or territory.
Can a raise or a new job reduce my government benefits?
A raise or new job can affect your benefits, but the timing depends on the program. Many income-tested benefits that the CRA administers, such as the Canada Child Benefit, are based on your income from the previous tax year. Other programs, such as EI and some provincial income assistance, may consider your current earnings. Benefits based on contributions, such as CPP retirement benefits, are not income-tested in the same way.
What can I do if my government benefit application is denied?
Read the decision letter to understand why your application was denied and whether you can request a review, reconsideration or appeal. Each program has its own process and deadline. If the instructions are unclear, contact the program administrator promptly and keep copies of your correspondence.
How can I check whether a government benefit message is legitimate?
Verify unexpected messages through the agency’s official website or a phone number you find independently. If the message claims to be from the CRA, follow its guidance on recognizing scams. Avoid using links or contact details in a suspicious message, especially if it asks for banking information or account passwords.